

The broad markets experienced volatility in the 3rd quarter with concerns over the impact of energy prices on inflation as well as CapEx spending by hyperscaler companies in the AI space driving technology stocks. The price of WTI Crude oil rallied sharply during the quarter by nearly 30%. In turn, interest rates spiked and the 10-year treasury increased from 4.41% to 5.29%. The aforementioned combined with elevated stock market valuations, seasonality weakness and political uncertainty with the upcoming elections has investors on edge.
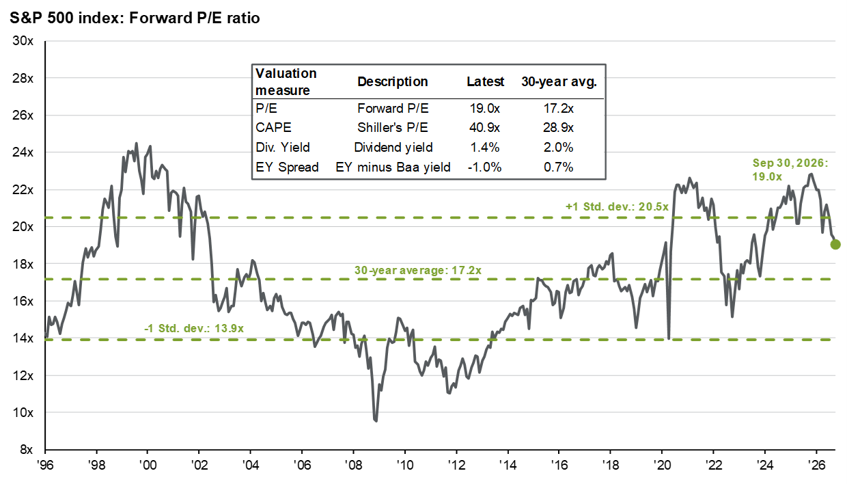
Market Valuations are Historically Elevated
Source: JP Morgan as of September 30, 2026
As is depicted in the chart above, the market measured by the S&P 500 Index is currently trading at above historical valuations. However, the multiples have come down due to a combination of a pullback of stocks from their highs as well as forward earnings revisions being more optimistic.
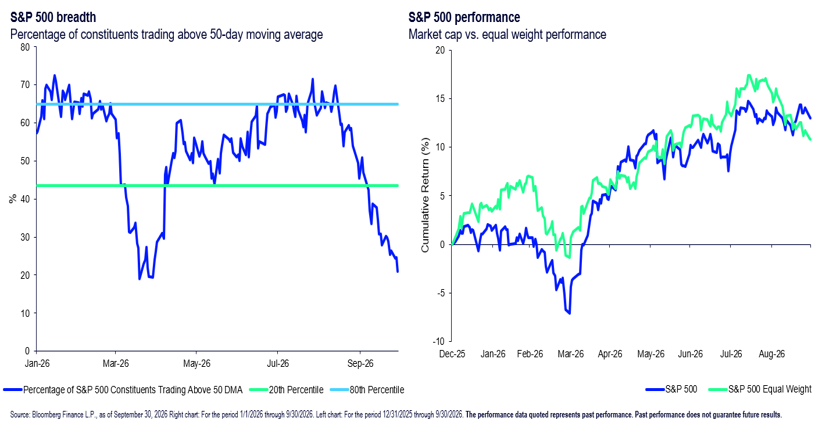
The technicals of the market have been weak, which seasonality is generally the case in the months of August and September. The following chart illustrates recent market breadth conditions. As of quarter’s end there were only about 25% of the stocks in the S&P 500 Index trading above their 50-day moving averages. In addition, the broader equal weighted S&P 500 Index vs. cap weighted index has reversed strength in the prior quarter.
U.S. Equity Breadth
Source: State Street Investment Management Chart Pack as of September 30,2026
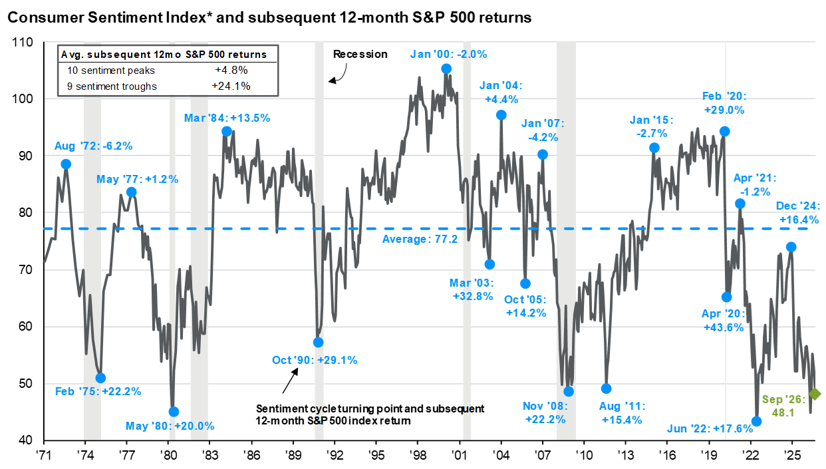
This overall weakness has led to consumer sentiment weakness. The following chart reflects consumer sentiment relative to the market performance going back to the early 70’s. As is depicted, there have been 10 sentiment peaks and 9 sentiment troughs over the period. Typically, the markets perform well coming off of a sentiment trough. The S&P 500 Index has averaged about 24% in the following 12 months after a sentiment trough.
Consumer Confidence and the Stock Market
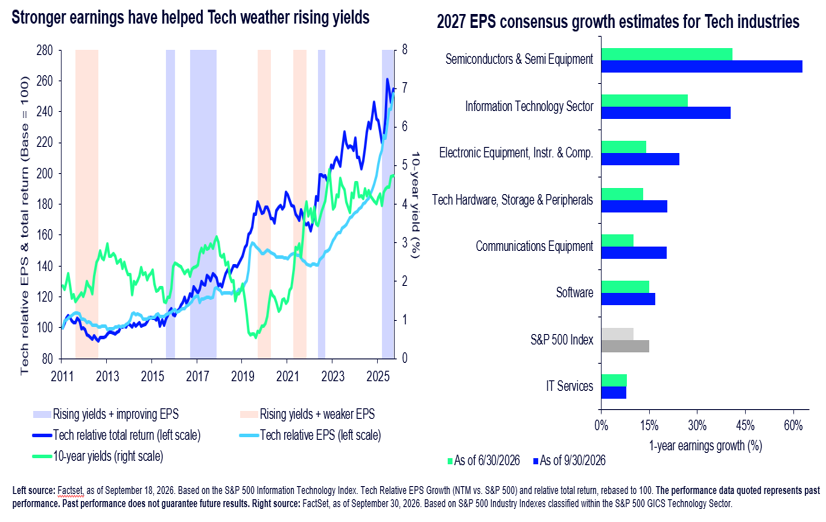
Technology Resilience and Forward Growth
Source: State Street Investment Management Chart Pack as of September 30, 2026
Regards,
Jeffrey R. Thompson
Chief Executive Officer
Fundamental Portfolios
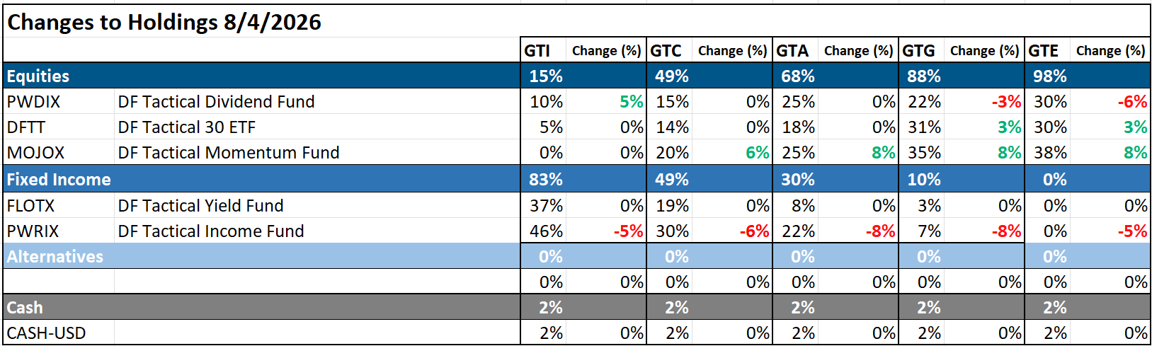
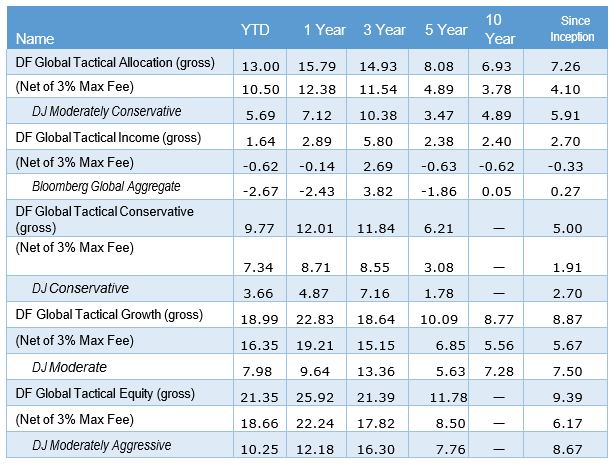
The investment committee continues to have an overall bullish viewpoint on the global markets and particularly in the U.S. We are maintaining our above average equity exposure at this point in the 4th quarter. The Global Tactical Portfolio suite did add equity exposure in early August across all risk portfolios at the portfolio allocation level. The portfolios pulled from its fixed income exposure opting for a more bullish stance. In the more aggressive portfolios (GTG and GTE) the investment committee shifted from dividend and value areas and added to momentum exposures. During the quarter, we did re-allocate within the underlying fund exposures. The momentum equity funds have rebalanced and reconstituted in the 3rd week in September with significant changes within the funds. The dividend fund did rebalance with minor changes otherwise. There were also changes in the fixed income allocations within the underlying funds. In July, our fixed income positioning reduced duration exposure by selling intermediate term treasuries and shifted to short term investment grade bond exposure. In September, we sold our high yield exposure as duration risk impacted not only longer duration investment grade asset classes but also high yield. It should be noted that after the quarter the investment committee added back duration exposure as the fixed income areas of the markets have become more attractive due to the pullback in areas of duration. Our Global Tactical Portfolios are having a strong year and are beating their benchmarks on a year-to-date basis. We will continue to monitor market trends and seek tactical opportunities to take advantage of any dislocations.
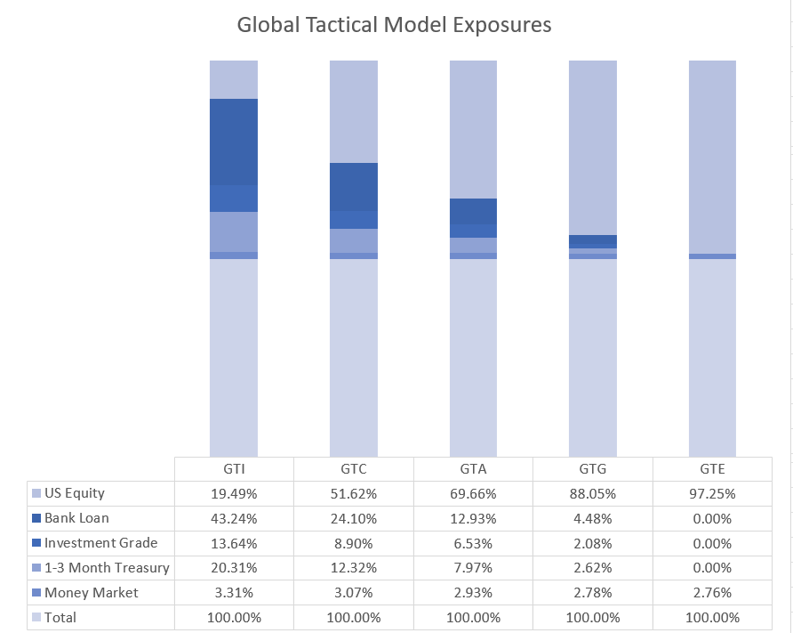
(Positioning as of 9/30/2026)
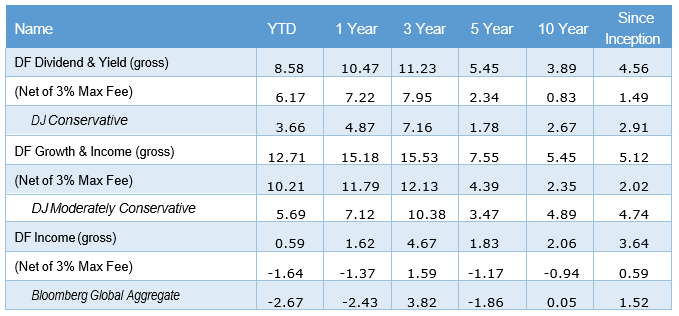
(Performance as of 9/30/2026)
Rules Based Portfolios
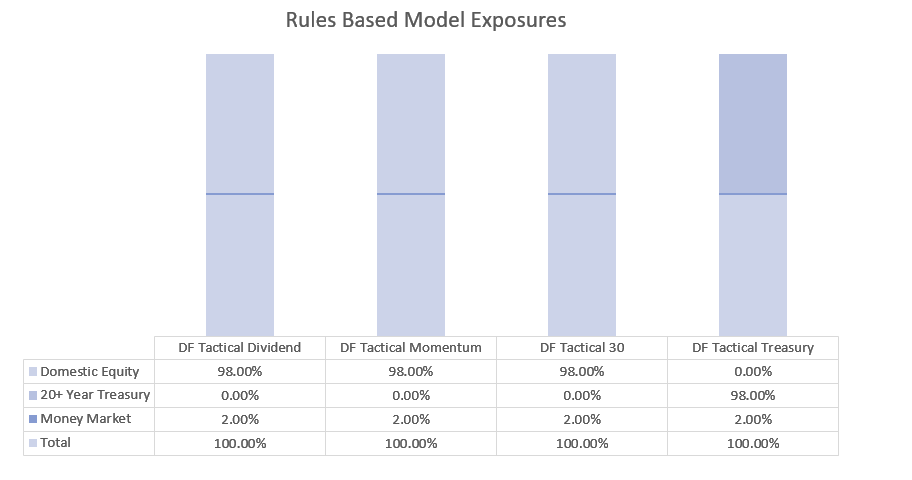
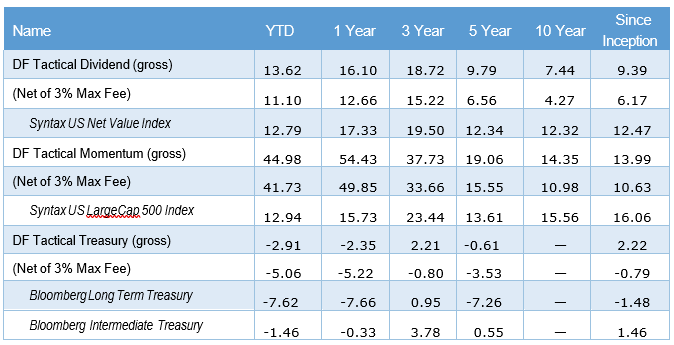
The DF Tactical Momentum and DF Tactical Dividend SMAs maintained a bullish position heading into the 3rd quarter of 2026. It should be understood that both strategies have tactical overlays that are designed to attempt to mitigate downside risk particularly in a deep recessive market environment. The signals are not designed to capture every ebb and flow and corrective pullback. Therefore, there were no defensive signals in the quarter. Both strategies are up double digits year to date. The DF Tactical Momentum SMA is having a strong year and is significantly outperforming its benchmark and the broad market in general. The attribution of the DF Tactical Momentum can largely be attributed to the technology sector and particularly to semiconductors and semiconductor equipment positions it held during the year. The portfolio as previously noted did reconstitute and rebalance in the 3rd week in September. The strategy did have significant portfolio changes and rolled about 90% of the portfolio. It should be noted that this is a high turnover portfolio and generally works best within a tax deferred account. In general, the DF Tactical Momentum SMA shifted away from the following areas: semiconductors, computer hardware, managed care and selected AI-infrastructure winners. The strategy shifted towards the following industries software, cybersecurity, cloud infrastructure, professional services, banking, wealth management and digital travel. The strategy does stay sector neutral to the broader market and adds alpha largely due to its underlying industry and constituent exposures.
The DF Tactical Dividend SMA had little changes other than the quarterly rebalance. It should be understood that this strategy reconstitutes on an annual basis and will do so in the 3rd week in March of 2027. We would be happy to provide full portfolio details for the DF Tactical Momentum and Dividend SMAs upon request.
The DF Tactical Treasury strategy did have a shift at the end of the quarter from intermediate term treasuries to long-term treasuries as our technical indicators tied to the credit asset classes had deteriorated. Subsequent to the quarter, after a profitable trade, the strategy shifted towards cash equivalents
(Positioning as of 9/30/2026)
(Performance as of 9/30/2026)
Blended Portfolios
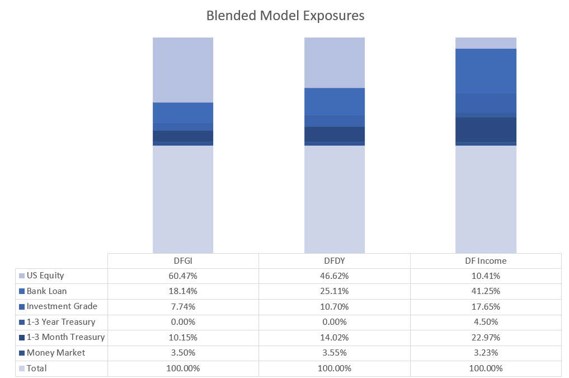
The blended portfolios combine our global macro fundamental research along with our rules based technical strategies. Currently, we are favoring U.S. equities and are tilted away from high yield credit and bank loans in favor of short-term treasury exposure and short-term investment grade bonds. The investment team will seek tactical opportunities to increase equity exposure but will also be ready to pull off risk should trends reverse.
(Positioning as of 9/30/2026)
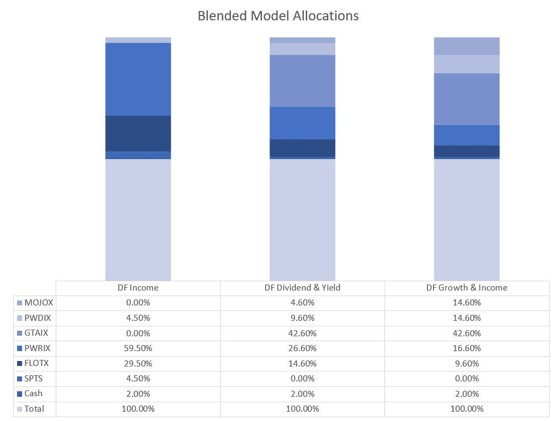
(Performance as of 9/30/2026)
You can get more information by calling (800) 642-4276 or by emailing AdvisorRelations@donoghueforlines.com.

Regards,
Jeffrey R. Thompson
Chief Executive Officer
Important Disclosures
Past performance is no guarantee of future results. Performance prior to January 1, 2018 was earned on accounts managed at a predecessor firm, JAForlines Global. The person primarily responsible for achieving that performance continues to manage accounts at Donoghue Forlines in a substantially similar manner. The material contained herein as well as any attachments is not an offer or solicitation for the purchase or sale of any financial instrument. It is presented only to provide information on investment strategies, opportunities and, on occasion, summary reviews on various portfolio performances. The investment descriptions and other information contained in this Markets in Motion are based on data calculated by Donoghue Forlines LLC and other sources including Morningstar Direct. This summary does not constitute an offer to sell or a solicitation of an offer to buy any securities and may not be relied upon in connection with any offer or sale of securities. The views expressed are current as of the date of publication and are subject to change without notice. There can be no assurance that markets, sectors or regions will perform as expected. These views are not intended as investment, legal or tax advice. Investment advice should be customized to individual investors objectives and circumstances. Legal and tax advice should be sought from qualified attorneys and tax advisers as appropriate. The calculation and presentation of performance has not been approved or reviewed by the SEC or its staff.
The DF Global Tactical Allocation Portfolio composite was created July 1, 2009. The DF Global Tactical Income Portfolio composite was created August 1, 2014. The DF Global Tactical Growth Portfolio composite was created April 1, 2016. The DF Global Tactical Conservative Portfolio composite was created January 1, 2018. The DF Global Tactical Equity Portfolio composite was created January 1, 2018. The DF Tactical Dividend Portfolio Composite was created on January 1, 2013. The DF Tactical Treasury Portfolio was created on August 1, 2017. The DF Tactical Momentum Portfolio Composite was created March 1, 2016. The DF Dividend & Yield Portfolio Composite was created December 1, 2011. The DF Growth & Income Portfolio Composite was created January 1, 2015. The DF Income Portfolio Composite was created June 1, 2008.
Results are based on fully discretionary accounts under management, including those accounts no longer with the firm. Individual portfolio returns are calculated monthly in U.S. dollars. These returns represent investors domiciled primarily in the United States. Past performance is not indicative of future results. Performance reflects the re-investment of dividends and other earnings.
Net 3% Returns
For all portfolios, net 3% returns are presented net of a hypothetical maximum total fee of three percent (3%). Actual fees applicable to an individual investor’s account will wary and no individual investor may incur a fee as high as 3%. Please consult your financial advisor for fees applicable to your account. Individual returns will vary.
Fee Schedule
The investment management fee schedule for all Fundamental and Blended portfolios is: Client Assets = All Assets; Annual Fee % = 0.00%. Actual investment advisory fees incurred may vary and should be confirmed with your financial advisor.
Each Fundamental and Blended portfolio includes holdings on which Donoghue Forlines may receive management fees as the advisor and/or subadvisor or from separate revenue sharing agreements. Please see the prospectuses for additional disclosures.
Investors should carefully consider the investment objectives, risks, charges, and expenses of mutual funds and ETFs. This and other information about a Fund is contained in its prospectus and should be read carefully before investing.
The investment management fee schedule for the DF Tactical Dividend and DF Tactical Momentum SMAs is: Client Assets = All Assets; Annual Fee % = 0.35%. Actual investment advisory fees incurred may vary and should be confirmed with your financial advisor.
The investment management fee schedule for the DF Tactical Treasury SMA is: Client Assets = All Assets; Annual Fee % = 0.25%. Actual investment advisory fees incurred may vary and should be confirmed with your financial advisor.
The DF Global Tactical Allocation Benchmark is the DJ Moderately Conservative Index. The DF Global Tactical Conservative Benchmark is the DJ Conservative Index. The DF Global Tactical Growth is the DJ Moderate Index. The DF Global Tactical Income Benchmark is the Bloomberg Global Aggregate Index. The DF Global Tactical Equity Benchmark is the DJ Moderately Aggressive Index. The DF Dividend & Yield Benchmark is the DJ Conservative Index. The DF Growth & Income Benchmark is the DJ Moderately Conservative Index. The DF Income Benchmark is the Bloomberg Global Aggregate Index. The Dow Jones Moderately Aggressive Index is a multi-asset index designed to reflect a portfolio with a moderate risk profile. It targets an 80% risk level, as measured by the downside risk of the Dow Jones Global Stock CMAC Index, over a 36-month period. This risk profile is achieved through an allocation of stocks, bonds, and cash. The Dow Jones Moderate TR Index measures the performance of returns on its total portfolios with a target risk level of moderate investors will take 60% of all stock portfolio risk. Its portfolios include three major asset classes: stocks, bonds, and cash. The weightings are rebalanced monthly to maintain the target level. The index is a subset of the global series of the Dow Jones Relative Risk Indices. The Dow Jones Moderately Conservative portfolio index is a member of the Dow Jones Relative Risk Index Series and is designed to measure a total portfolio of stocks, bonds, and cash, allocated to represent an investor’s desired risk profile. The Dow Jones Moderately Conservative Portfolio index risk level is set to 40% of the Dow Jones Global Stock CMAC Index’s downside risk (past 36 months). The Bloomberg Global Aggregate Index is a broad-based flagship benchmark that measures the investment grade, us dollar-denominated, fixed-rate taxable bond market. The index includes Treasuries, government-related and corporate securities, fixed-rate agency MBS, ABS and CMBS (agency and non-agency).
The DF Tactical Dividend Benchmark is the Syntax US Net Value Index. The DF Tactical Momentum Benchmark is the Syntax US LargeCap 500 Index. The DF Tactical Treasury Benchmarks are the Bloomberg Long Term Treasury Index and the Bloomberg Intermediate Treasury Index. The Syntax US Net Value Index is a type of stock market index that tracks the performance of the US equity market, specifically focusing on value-oriented companies. It measures the net asset value (NAV) of a portfolio holding large-cap US equities, typically companies that are considered value-oriented. The Syntax US LargeCap 500 Index float market cap weights the 500 largest public US companies as ranked by their float market caps, subject to rank buffers and liquidity screens. Companies are defined as US According to Syntax’s proprietary country classification methodology considering regulatory filings, currencies of accounting and distribution, and tax havens. The Bloomberg US Long Treasury Index, Bloomberg US Intermediate Treasury Index, are for comparison purposes only. Bloomberg US Long Term Treasury Index measures the performance of US treasury bonds with long term maturity. The credit level for this index is investment grade. Bloomberg US Intermediate Term Treasury Index measures the performance of US treasury notes with intermediate term maturity. The credit level for this index is investment grade.
Index performance results are unmanaged, do not reflect the deduction of transaction and custodial charges or a management fee, the incurrence of which would have the effect of decreasing indicated historical performance results. You cannot invest directly in an Index. Economic factors, market conditions and investment strategies will affect the performance of any portfolio, and there are no assurances that it will match or outperform any particular benchmark.
Policies for valuing portfolios, calculating performance, and preparing compliant presentations are available upon request. For a compliant presentation and/or the firm’s list of composite descriptions, please contact 800-642-4276 or info@donoghueforlines.com.
Donoghue Forlines LLC is a registered investment adviser with the United States Securities and Exchange Commission in accordance with the Investment Advisers Act of 1940. Registration does not imply a certain level of skill or training.


